Refinance Break-Even
Compares a current mortgage to a refinance: the new payment, monthly savings, when the costs pay off and the total over both loans.
Open the Refinance Break-EvenStep by step
- 1
Enter the current loan
Type the balance, rate and years left.
- 2
Enter the new loan
Type the new rate, term, closing costs and points. Turn on Roll costs into the loan if they won't be paid in cash.
- 3
Add the optional items
Under More details, enter the current principal and interest payment if you know it (leave 0 to calculate it), and any cash out.
- 4
Download the PDF
If you like, pick a client and property in the Client & property menu above the button so the PDF says who it's for. It doesn't change your numbers. Download the Refinance Break-Even PDF with your name, photo and phone on it; it saves to the Results tab.
- 5
Send it to clients
The Share tab has your branded link for this calculator, with buttons to copy, text or email it. Clients can run it there on their own.
Reading the results
The top number is the monthly savings, with the break-even in months. Below are both payments, the refi costs, and interest left on each loan, then a line saying whether the refi saves or costs more over the life of the loans.
Savings over time shows payments saved after 1, 3, 5 and 10 years, and a second column that also counts the difference in what's still owed.
Estimates to check
A longer new term can lower the payment and still cost more overall. Rates and costs are estimates; the lender's Loan Estimate has the real numbers.
What the PDF has
The current loan, the new loan, the difference with break-even, and the savings-over-time table.
On your branded page
Clients can run this calculator on your branded page, techybroker.com/b/{handle}, under Buying. To download the PDF they give a name and an email or phone. That adds them to your clients, and their runs and downloads show in Activity.
Questions
Does rolling costs into the loan change the break-even?
No. Break-even uses the full cost either way. Rolling them in raises the new loan and payment.
Why does it say it costs more even though the payment drops?
Restarting a longer term adds years of payments, which can add up to more in total.
Related
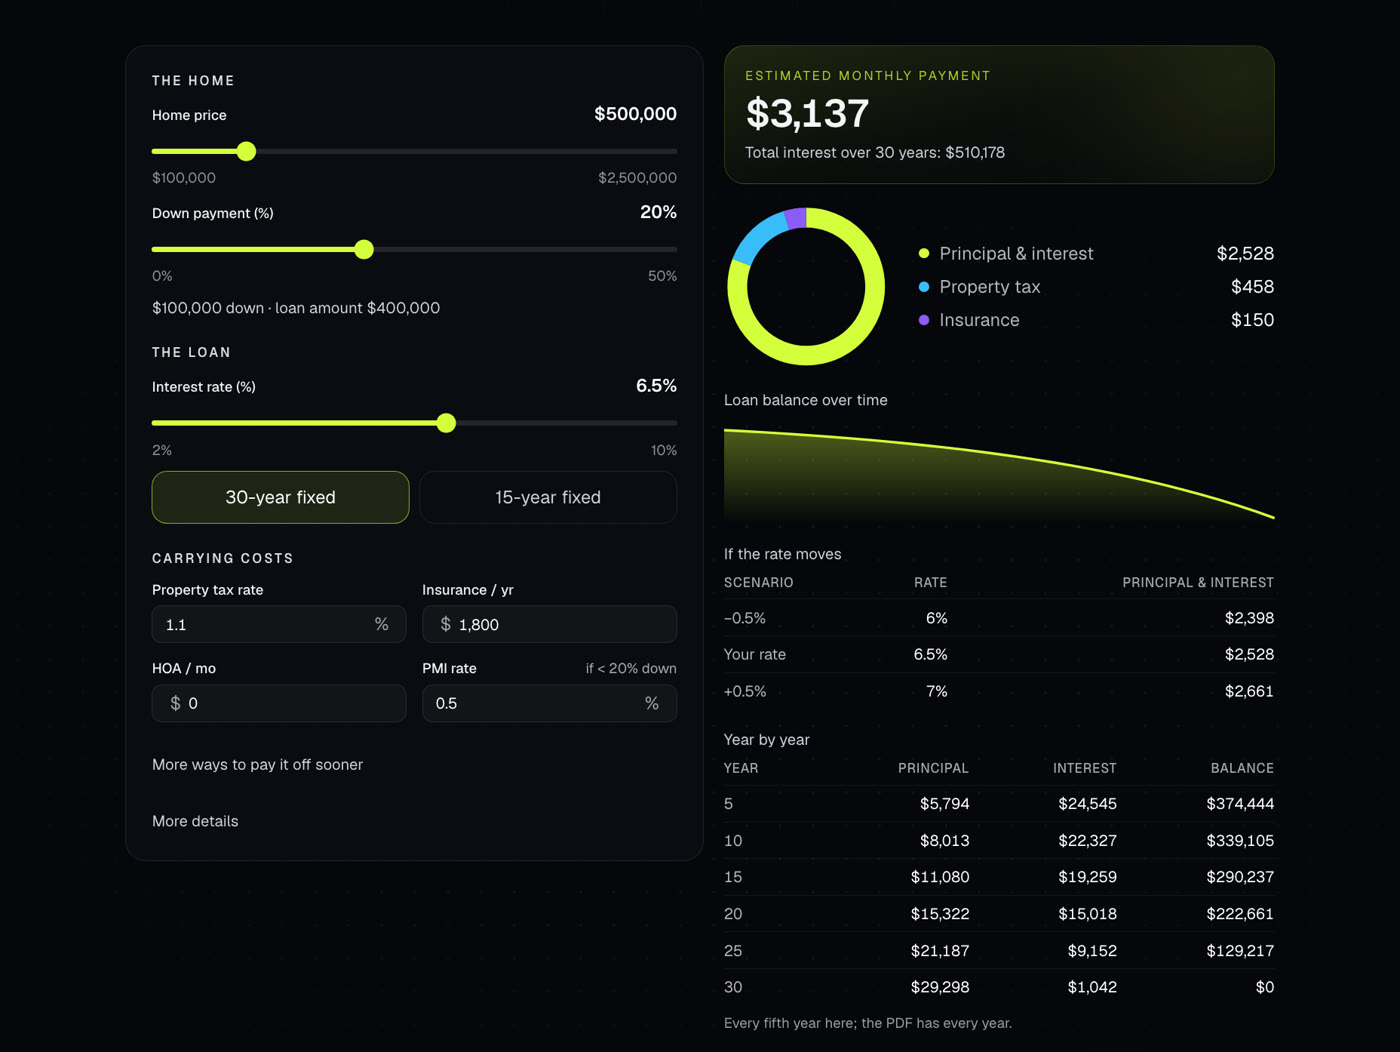
Shows the full monthly payment with taxes, insurance, PMI and HOA, plus the loan balance over time. Also handles extra payments and discount points.
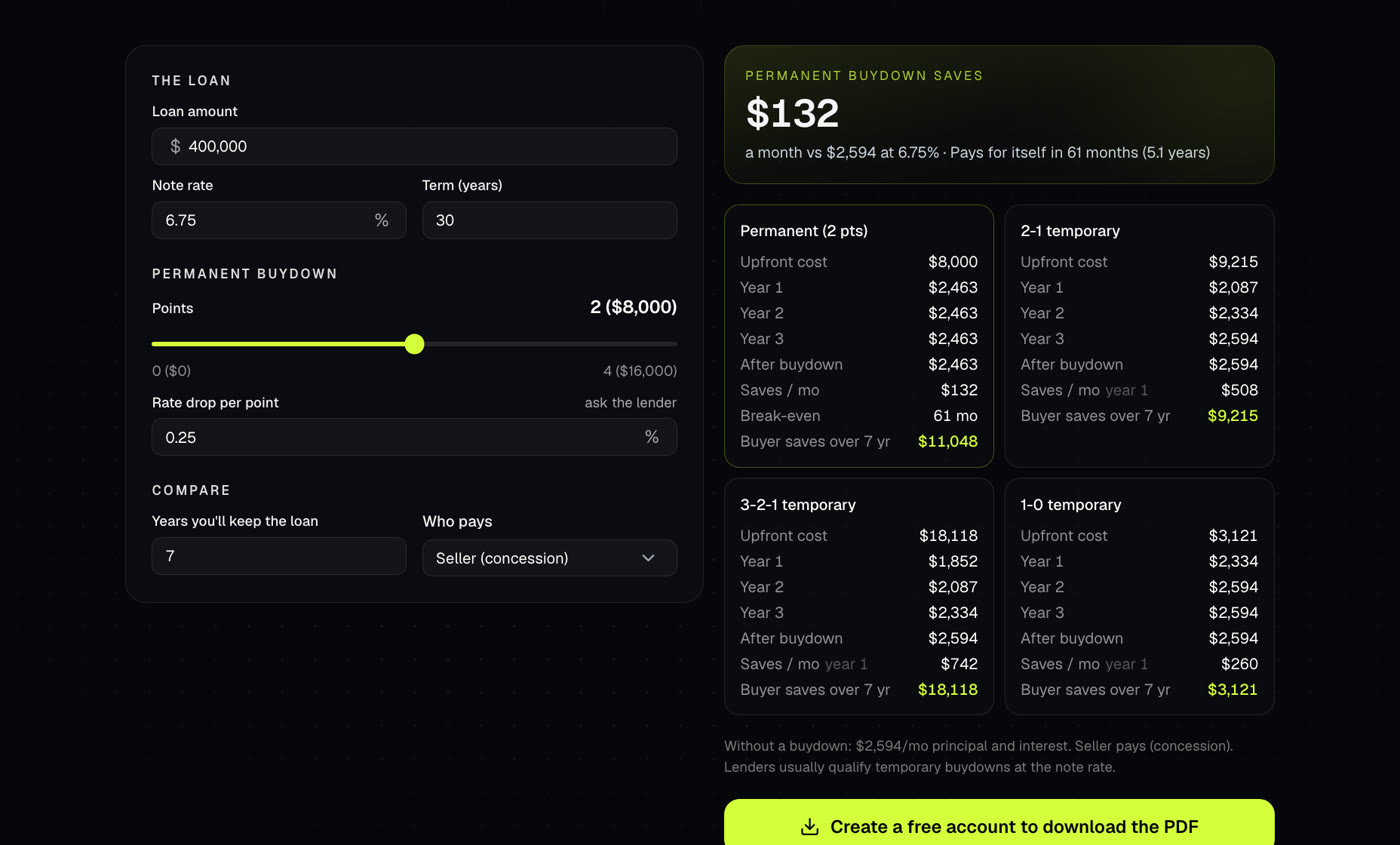
Compares a permanent buydown with points against 2-1, 3-2-1 and 1-0 temporary buydowns: cost, payments, break-even and savings.

Every PDF you download is saved, so you can preview it, download it again with your current brand, or reopen it with the same numbers.